Williams | Robinson | Wiggins
insights - all things legal
The national firearms act: is the 1934 gun law still enforceable?
Ninety years of the National Firearms Act — the injunction that interrupted it, and the stand-down that followed
For more than ninety years, a federal law most gun owners have never read has decided which firearms an American may buy over the counter and which require months of paperwork, fingerprints, and a federal tax stamp. That law — the National Firearms Act of 1934 (the "NFA") — is now, for the first time in its history, partly unenforceable. On August 5, 2026, a federal district court in Texas held that the NFA's registration and approval requirements for suppressors, short-barreled rifles, short-barreled shotguns, and "any other weapons" exceed Congress's powers under the Constitution. The reason is not the Second Amendment. It is the humbler power that has carried the NFA since 1934 — the power to tax — and what happens to that power when the tax is cut to zero. The government did not appeal, and on October 9, 2026, ATF announced that it will no longer enforce those requirements against anyone, nationwide. Keep reading for the history, the ruling, the stand-down, and what it means for Missouri gun owners.
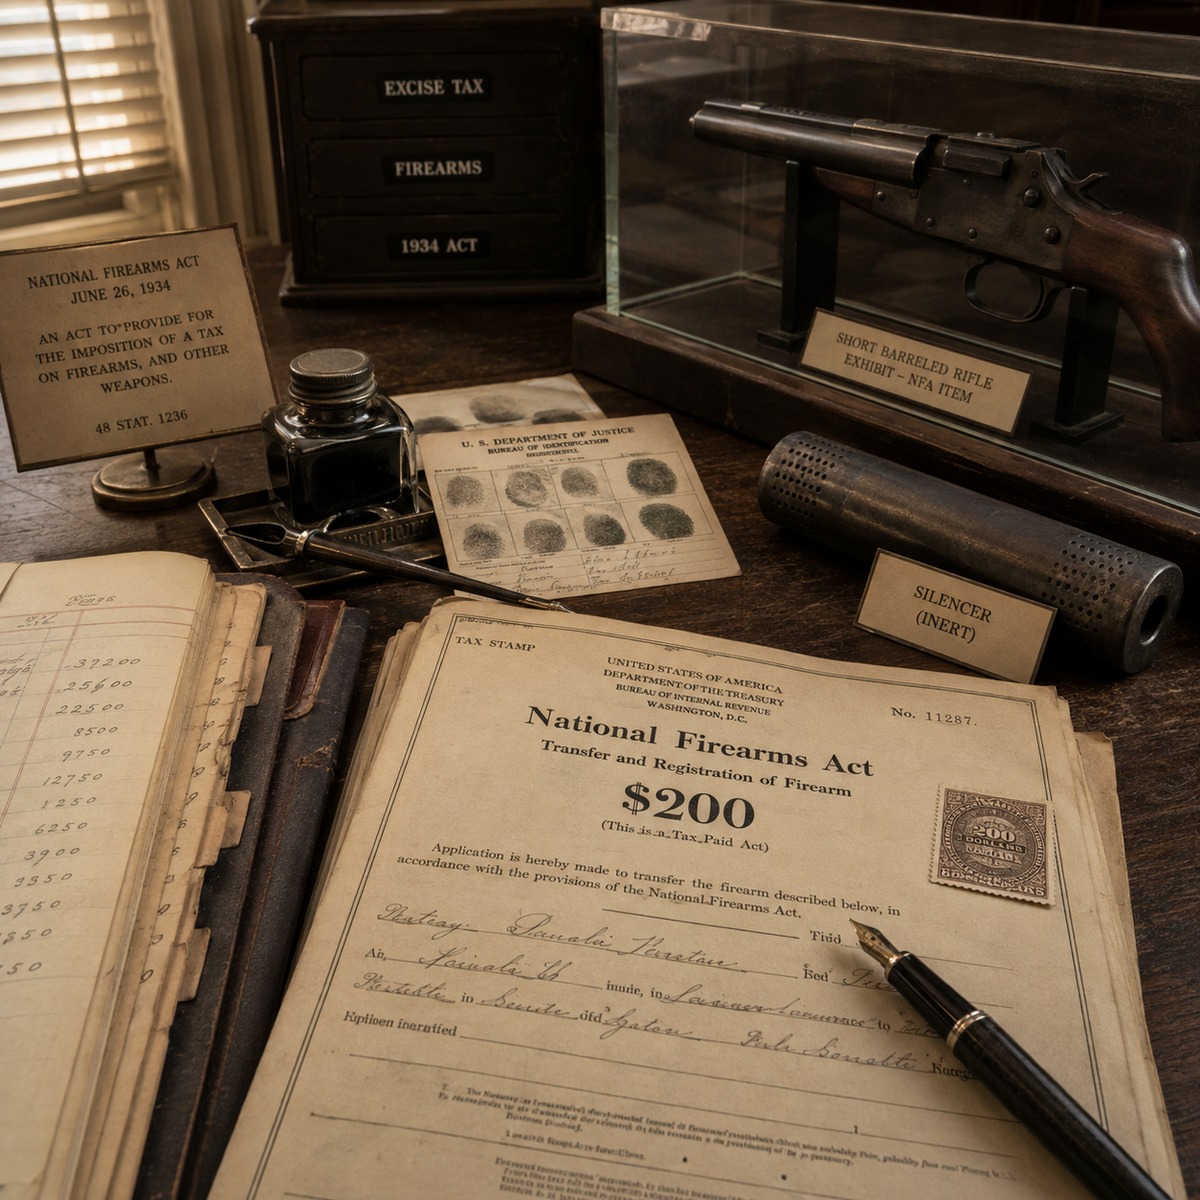
What the NFA does. Despite its name, the NFA has never regulated most firearms. It applies to a short list: machine guns, rifles with barrels shorter than sixteen inches, shotguns with barrels shorter than eighteen inches, suppressors (silencers), "destructive devices" such as grenades and artillery, and a catch-all category called "any other weapons." To make or receive one of these items, a person must apply to the Bureau of Alcohol, Tobacco, Firearms and Explosives ("ATF") on a government form with fingerprints and a photograph, wait for approval, and — until this year — pay a $200 tax. The firearm is then registered to its owner in a central federal registry. Receiving or possessing an NFA firearm that is not registered to you is a federal felony punishable by up to ten years in prison. § 5861, § 5871.
What is an "any other weapon"? The NFA's strangest category deserves a word of its own, because it is a specialized federal classification in its own right — defined in 26 U.S.C. § 5845(e) and administered by ATF. An "any other weapon," or AOW, is, roughly, a concealable firearm that does not fit the ordinary molds of pistol, rifle, or shotgun. (See definition in § 2.1.5, ATF NFA Handbook.) The classics are disguised guns — pen guns, cane guns, wallet guns — along with smooth-bore pistols designed to fire shotgun shells, certain short combination guns, and, under ATF's classification rulings, an ordinary handgun fitted with a vertical foregrip. Ordinary pistols and revolvers with rifled bores are expressly excluded. Two things made AOWs peculiar even within the NFA: classification often turns on ATF determinations rather than on anything obvious about the firearm — attaching a small accessory to a pistol could transform it into an NFA firearm — and Congress taxed AOW transfers at just $5, a bargain next to the $200 everything else carried (though the $200 making tax applied all the same). The 2025 tax cut zeroed the AOW taxes along with the rest, and the new injunction reaches AOWs — subject to the wrinkle noted below.
Why 1934? The NFA was Congress's answer to the gangland violence of the Prohibition era — the age of Dillinger, Bonnie and Clyde, and the Thompson submachine gun. But in 1934 the Supreme Court still read Congress's power over interstate commerce narrowly, so a direct federal ban was thought to be off the table. Attorney General Homer Cummings instead modeled the bill on the Harrison Narcotics Tax Act of 1914, which had survived constitutional challenge as a tax measure, telling Congress that the drafters "followed the Harrison Anti-Narcotic Act in language so as to get the benefit of any possible interpretation that the courts may have made of that act." The $200 transfer tax was not an arbitrary number: it matched the price of a machine gun in 1934 — the equivalent of nearly $5,000 today. The tax was never adjusted for inflation. It was still $200 when Congress finally addressed it ninety-one years later.
The Supreme Court signs off. The constitutional test came quickly. Max Sonzinsky, convicted of dealing in firearms without paying the NFA's dealer tax, argued the "tax" was really a penalty — a regulation of local affairs dressed in revenue clothing. In Sonzinsky v. United States, 300 U.S. 506 (1937), the Supreme Court disagreed:
Here the annual tax of $200 is productive of some revenue. We are not free to speculate as to the motives which moved Congress to impose it, or as to the extent to which it may operate to restrict the activities taxed. As it is not attended by an offensive regulation, and since it operates as a tax, it is within the national taxing power.
Note the premise doing the work: the tax was "productive of some revenue." The Court upheld the NFA because its tax, whatever else it accomplished, raised money. That premise would hold for the next eighty-nine years.
The Second Amendment's odd first case. Two years later came the only Second Amendment decision the Supreme Court would issue on the NFA for nearly seventy years. Jack Miller was indicted for transporting an unregistered short-barreled shotgun across state lines; the district court quashed the indictment on Second Amendment grounds, and the government appealed. In United States v. Miller, 307 U.S. 174 (1939), the Supreme Court reversed:
In the absence of any evidence tending to show that possession or use of a "shotgun having a barrel of less than eighteen inches in length" at this time has some reasonable relationship to the preservation or efficiency of a well regulated militia, we cannot say that the Second Amendment guarantees the right to keep and bear such an instrument.
Miller was a strange case by any measure: no brief was filed and no lawyer appeared on Miller's behalf, and Miller himself was dead before the decision issued. The modern Supreme Court has described the opinion as "virtually unreasoned." District of Columbia v. Heller, 554 U.S. 570, 624 & n.24 (2008). Yet for decades, Sonzinsky and Miller together were treated by the lower courts as settling the NFA's validity.
A Fifth Amendment detour and the 1968 rewrite. The next crack appeared somewhere unexpected. Because the original Act required the possessor of an unregistered firearm to register it, a person holding one illegally had to choose between registering — and confessing a crime — or staying silent and committing a new one. In Haynes v. United States, 390 U.S. 85 (1968), the Supreme Court held that prosecution for failing to register violated the Fifth Amendment privilege against self-incrimination. Congress responded within the year. Title II of the Gun Control Act of 1968 rebuilt the NFA: only a lawful maker or transferor may apply, ATF itself registers the firearm when it approves the application, and a $200 making tax was added alongside the transfer tax. The Supreme Court blessed the rewritten scheme in United States v. Freed, 401 U.S. 601 (1971). That 1968 architecture — apply, pay, await approval, possess — is the system every NFA owner knows today.
The machine gun freeze — and a warning shot. In 1986, the Firearm Owners' Protection Act closed the registry to new machine guns: under 18 U.S.C. § 922(o), civilians may possess only machine guns lawfully registered before May 19, 1986. The freeze produced a little-noticed curiosity. Because the government would no longer accept the tax for a newly made machine gun, a federal district court held in 1991 that the NFA's registration provisions could no longer be enforced as to post-1986 machine guns — with the tax uncollectible, the taxing-power rationale was gone. United States v. Rock Island Armory, Inc., 773 F. Supp. 117 (C.D. Ill. 1991). The decision drew little attention at the time. It turned out to be a preview.
The modern era. In District of Columbia v. Heller, the Supreme Court recognized the Second Amendment as an individual right, and in New York State Rifle & Pistol Association v. Bruen, 597 U.S. 1 (2022), it directed courts to test gun laws against text and historical tradition. Even so, Second Amendment challenges to the NFA mostly failed — courts reasoned, for example, that suppressors are accessories rather than protected "arms." United States v. Cox, 906 F.3d 1170 (10th Cir. 2018). The quieter question was whether the NFA still worked as a tax. In the "Obamacare" decision, National Federation of Independent Business v. Sebelius, 567 U.S. 519 (2012), the Supreme Court reaffirmed that the taxing power has limits — chief among them, that a tax must actually raise at least some revenue. The Eleventh Circuit later acknowledged that Sonzinsky had never resolved the validity of the modern Act's other provisions, United States v. Bolatete, 977 F.3d 1022 (11th Cir. 2020), and a Texas district court applied Sebelius to strike down two Civil War-era distilling statutes that defined crimes without raising revenue. Hobby Distillers Ass'n v. Alcohol & Tobacco Tax & Trade Bureau, 740 F. Supp. 3d 509 (N.D. Tex. 2024). Scholars laid out the roadmap in detail. See Charles K. Eldred, The National Firearms Act is an Unconstitutional Tax, 25 Wyo. L. Rev. 191 (2025). The pieces were in place; all that was missing was for the tax to disappear.
Congress cuts the tax to zero. It disappeared on July 4, 2025. In the budget legislation known as the One Big Beautiful Bill Act, Pub. L. No. 119-21, Congress reduced the NFA's $200 making and transfer taxes to zero for suppressors, short-barreled rifles, short-barreled shotguns, and "any other weapons," effective January 1, 2026. (The $200 tax remains for machine guns and destructive devices.) The registration, fingerprints, photographs, and ATF approval requirements all stayed on the books. The result was a statute that regulated exactly as before but, for those four categories, taxed nothing — this from a scheme that had collected roughly $145 million in making and transfer taxes in fiscal year 2024. Lawsuits challenging the remains of the scheme were filed within days.
The injunction. On August 5, 2026, in Silencer Shop Foundation v. Bureau of Alcohol, Tobacco, Firearms and Explosives, No. 6:25-CV-056-H (N.D. Tex. Aug. 5, 2026), consolidated with Jensen v. ATF, Judge James Wesley Hendrix held that with the tax at zero, the registration and approval apparatus built to collect it no longer rests on any enumerated power. From the opening page of the opinion:
At that time, the NFA possessed the key feature of any tax: It produced some revenue for the government. But that is no longer true. … Because today's NFA does not generate any revenue from untaxed firearms, its regulatory provisions cannot be upheld under the taxing power.
Echoing Sonzinsky in reverse, the court declared the NFA's transfer-approval, making-approval, and registration provisions — and the crimes that enforce them — unconstitutional as applied to suppressors, short-barreled rifles, short-barreled shotguns, and "any other weapons," and enjoined their enforcement in a final judgment entered the same day. The court did not reach the plaintiffs' Second Amendment claims; the decision rests entirely on the taxing power. The judgment was stayed seven days to let the government seek relief from the Fifth Circuit. The government sought none, the stay expired on August 12, 2026, and the injunction took effect. The government then let its sixty-day window to appeal close on October 5, 2026, without filing a notice of appeal — the Solicitor General had told the Senate Judiciary Committee on September 24 that the Department "has determined not to file an appeal" — and the judgment is final.
Who is actually covered by the injunction? This is where caution was essential. The injunction itself is not nationwide. It protects the plaintiffs — firearms businesses, gun-rights organizations, individual owners, and a coalition of fifteen states — together with the states' agencies and political subdivisions and the organizations' members and the businesses' customers, current and future. By name, the gun-rights organizations are Gun Owners of America, the Firearms Regulatory Accountability Coalition, and Gun Owners Foundation, joined on the Jensen side of the consolidated case by the Texas State Rifle Association, FPC Action Foundation, and the Citizens Committee for the Right to Keep and Bear Arms; the business plaintiffs are B&T USA, Palmetto State Armory, SilencerCo Weapons Research, and Hot Shots Custom; and the lead plaintiff, Silencer Shop Foundation, is a Texas nonprofit that sued in its own right. (One wrinkle: relief as to "any other weapons" runs only to the Silencer Shop side of the consolidated case.) The court was equally clear about who is not covered: it declined to extend protection to the associations' "supporters" — members only — or to resident family members of covered persons, and customer protection reaches only transactions with the plaintiff businesses and the associations' commercial members, not everything a covered customer may later do with NFA items. Nor does residency help by itself: a citizen of a plaintiff state is not automatically protected — on the state side, the injunction covers only the state itself, its agencies, and its political subdivisions, not its residents. Missouri is not among the plaintiff states. Under the injunction alone, a Missouri gun owner is covered, if at all, only through membership in a plaintiff organization or as a customer of a covered business, and proof of that status may matter someday. Machine guns and destructive devices remain fully regulated — their $200 tax still raises revenue, so the ruling does not touch them. And the Gun Control Act of 1968, a separate law resting on the commerce power, still applies to every firearm: dealer licensing, background checks, interstate transfer rules, and prohibited-person rules are all unchanged.
ATF stands down — nationwide. The injunction's limits came to matter less on October 9, 2026. That day, with the appeal deadline behind it and forty-seven members of Congress on record asking for nationwide application, ATF's Director issued an open letter to all federal firearms licensees and the public, with accompanying questions-and-answers on ATF's website. Although the injunction "applies only to plaintiffs and certain other specified persons," the letter explains, the Department "has determined to exercise its enforcement discretion to create greater uniformity," consistent with a statement by the Attorney General the same day. Effective October 9, ATF "will no longer require individuals to seek ATF approval under the NFA before making or transferring short-barreled rifles, short-barreled shotguns, silencers, and 'any other weapon[s],'" and will no longer require those items to be registered — policies that "apply uniformly to anyone otherwise subject to these requirements, not just to the plaintiffs in the litigation." The practical result is that a suppressor or short-barreled firearm can now be transferred by a licensed dealer on the ordinary Form 4473 and background check, with no Form 1 or Form 4, no fingerprints, no waiting period, and no stamp. ATF will keep administering the registry "on a voluntary basis," accepting Forms 1, 3, and 4 from anyone who chooses to file, and existing registrations stand. The letter is equally explicit about five things the stand-down does not reach: the special occupational tax on NFA manufacturers, importers, and dealers; machine guns and destructive devices, which remain fully regulated; the Gun Control Act, so prohibited-person, recordkeeping, and background-check rules apply to every one of these items exactly as before; the Gun Control Act's separate restrictions on transporting and selling short-barreled rifles and shotguns across state lines — owners should keep filing Form 20 before interstate travel, and ATF is writing new regulations for dealer transfers of those firearms, not enforcing the dealer-sale restriction in the interim; and state and local law, discussed next.
So — can you put away the paperwork? Closer than before, but not without advice, and three cautions belong in the same breath. First, the nationwide stand-down is policy, not law. The statute is still on the books, the only court order is party-limited, and ATF's own guidance warns that a material change in the legal or factual circumstances — a new federal law, for example — could bring renewed enforcement, with no assurance that items acquired in the meantime would be grandfathered or registered after the fact. Congress could rebuild the NFA's constitutional footing overnight by restoring even a nominal tax, and a future Attorney General could rescind the policy with a memorandum. Anyone within the injunction's protected class should keep proof of that status; it is the only protection that does not depend on the executive branch's continued forbearance. Second, state and local law operates independently of both the ruling and the policy. Possession of NFA items may be affected or restricted by state statutes and local ordinances (see, for example, § 571.020, RSMo, which bans NFA items unless permitted under applicable federal law — and a statute written on the assumption of federal registration does not answer, by itself, how an unregistered item that federal authorities have simply chosen not to prosecute will be treated). ATF's guidance acknowledges that it cannot say how state authorities will view unregistered items — most state prohibitions carve out only items "possessed in compliance with or registered under federal law" — and it is unsure whether the federal safe harbor for travelers transporting firearms through a hostile state, 18 U.S.C. § 926A, will be applied to unregistered NFA items at all. Several states ban suppressors or short-barreled firearms outright, no matter what federal law requires, and a licensed dealer still may not transfer a firearm in violation of state or local law. Third, do not dissolve a gun trust. Existing registrations remain valid, a trust still governs who may possess the items it holds and how they pass at death, and if enforcement ever resumes, the registered item is the one with nothing to explain. For the same reasons, the prevailing view among practitioners is that the prudent course, for now, is to keep registering voluntarily — ATF will still accept the forms, the cost is a wait rather than a tax, and a registered item is protected whichever way the courts or Congress finally resolve the question. The paperwork is optional today; the careful owner treats it as insurance until the issue is settled for good.
Did you know? The above information is presented by Williams | Robinson | Wiggins as a public service and to generally outline the law in a particular area. It is not provided and is not intended as legal advice tailored to you or to your unique situation. Every legal matter depends upon specific facts which an attorney hired by you must consider in forming legal opinions and advice.
Need more information? If you own NFA-regulated items, are considering acquiring one, or want to review how you or your gun trust holds and transfers them, you may contact us at(573) 341-2266 to obtain more detailed assistance.
J Kent Robinson
Of counsel with Williams | Robinson | Wiggins, Kent has practiced law since 1979. He spends most of his time being retired and, in his free time, working on banking law and business transactions.
Contact
Joseph W Rigler
Of Counsel with Williams | Robinson | Wiggins, Joe's civil litigation practice includes representing clients in automobile collisions, premises liability, medical neglect, and products liability matters.